Best overall starting point: a dealership financing discussion. Best for existing members: a credit union. Best budget approach: a smaller used-RV loan. The best RV financing for bad credit in 2026 is the affordable offer you qualify for after comparing borrowing costs, ownership expenses, and the RV itself—not the offer with the lowest monthly payment.
- Recreation USA is best for Myrtle Beach-area RV buyers seeking a local dealership financing discussion, not guaranteed approval.
- Compare dealership financing, credit unions, and bank RV loans using written terms rather than advertised monthly payments.
- A smaller used travel trailer can reduce the amount borrowed, but inspect its condition before choosing financing.
- A co-borrower shares repayment responsibility; credit approval does not prove that an RV fits your household budget.
Why this matters
Bad credit does not turn every RV financing offer into a good deal. A longer repayment term can lower the monthly payment while increasing total interest, and an affordable loan payment does not cover insurance, storage, maintenance, or camping expenses.
Recreation USA is a family-owned dealership with two lots in the Myrtle Beach, South Carolina area, offering new and used RVs, financing, trade-ins, parts, and service. Its wholesale-to-you positioning and no hidden freight or prep fees address dealership pricing transparency; you still need to examine the lender's terms separately.
Recreation USA is best for Myrtle Beach-area RV buyers seeking a local dealership financing discussion, not guaranteed approval. For shoppers in Conway, the Carolinas, and nearby states, that conversation should start with the amount you can afford—not the largest trailer a lender will finance.
What makes the best RV financing for bad credit?
Use these criteria to judge any 2026 offer before choosing a financing route:
- Total borrowing cost: Compare the annual percentage rate, finance charge, and total payments. A monthly payment alone cannot show the full cost.
- Payment fit: Leave room for household bills, insurance, maintenance, storage, and travel. Approval is a lender decision; affordability is yours.
- Vehicle eligibility: Ask whether the lender finances the RV's type, age, condition, and intended use before submitting an application.
- Application clarity: Confirm whether checking eligibility requires a hard credit inquiry and whether an initial estimate is a final approval.
- Contract flexibility: Check prepayment terms, required products, and any conditions attached to the offer. Get explanations in writing.
- Purchase readiness: Confirm towing compatibility and inspect a used RV before committing to its financing.
These criteria favor a loan you understand and can repay. They do not favor the biggest floorplan, the fastest approval, or the longest available term.
RV financing options at a glance
The ranking below compares financing approaches, not named lenders. Each approach serves a different buyer need, and the written offer determines whether it deserves your business.
| Rank and option | Best for | Standout feature | Key limitation |
|---|---|---|---|
| 1. Dealership financing discussion | Buyers matching an RV purchase with financing | Discuss the vehicle, trade-in, and financing together | Approval and loan terms remain lender decisions |
| 2. Credit union RV loan | Existing members seeking a direct lender quote | A separate offer from a membership-based lender | Membership and RV eligibility requirements apply |
| 3. Bank RV loan | Buyers wanting an independent comparison | Separate the borrowing decision from the dealership visit | Not every bank finances every RV or credit profile |
| 4. Co-borrower application | Buyers genuinely sharing the debt | Another applicant shares repayment responsibility | Both borrowers take on financial risk |
| 5. Smaller used-RV loan | Buyers prioritizing a lower amount borrowed | Match a less expensive purchase to a tighter budget | Condition and repair needs require close inspection |
1. Dealership financing: best for coordinating the purchase
A dealership financing discussion puts the RV, trade-in, and borrowing questions in the same conversation. It is a practical starting point when you still need to choose between a travel trailer and a fifth wheel, or between new and used.
Recreation USA offers RV financing alongside sales and trade-ins. Ask what the application involves, who makes the credit decision, and which written terms you will receive before signing. Do not treat a discussion or preliminary estimate as a final loan approval.
Dealership financing pros:
- Discuss the selected RV and financing together.
- Review how a trade-in affects the proposed purchase.
- Ask vehicle questions before committing to an application.
- Connect the purchase discussion with parts and service needs.
Dealership financing cons:
- The dealership conversation does not guarantee lender approval.
- A convenient payment quote still needs a total-cost comparison.
- Trade-in debt and optional products can complicate the amount financed.
Best for: Buyers who want help coordinating an RV purchase and financing discussion in the Myrtle Beach area.
Verdict: Hold until you have written loan terms and an itemized purchase agreement. Convenience is useful; it is not a substitute for comparing offers.
2. Credit union RV loans: best for existing members
A credit union is a direct-lender option to investigate if you already belong to one. Ask whether it offers RV loans and whether it will consider your credit history and chosen vehicle before starting a formal application.
An existing membership gives you a place to begin, not a promise of approval or a better rate. The credit union's written offer must stand on its own against the alternatives.
Credit union RV loan pros:
- Provides a separate quote for comparison.
- Lets you discuss borrowing before choosing a dealership purchase.
- Gives existing members a direct point of contact.
Credit union RV loan cons:
- Membership requirements apply.
- Vehicle restrictions can exclude a particular used RV.
- Membership does not override credit underwriting.
Best for: Existing credit union members who want to ask their own institution about RV financing.
Verdict: Hold until membership, vehicle eligibility, and final terms are confirmed. Do not assume a credit union wins simply because it is a credit union.
3. Bank RV loans: best for an independent comparison
A bank RV loan gives you another way to separate the financing decision from the vehicle selection. Start by asking whether your bank offers secured RV financing and considers applications with your credit circumstances.
If the bank provides preapproval, read its conditions. Vehicle information, documentation, or other requirements can still affect whether the proposed purchase qualifies.
Bank RV loan pros:
- Adds an independent offer to your comparison.
- Helps establish a borrowing limit before shopping.
- Lets you examine financing without choosing a dealership-arranged offer.
Bank RV loan cons:
- Your bank might not offer a suitable RV loan.
- An existing account does not guarantee credit approval.
- Preapproval can include conditions that the selected RV must meet.
Best for: Buyers who want a direct-lender reference point before accepting financing tied to an RV purchase.
Verdict: Hold until the bank confirms the specific vehicle and final loan terms. Compare the same purchase amount and repayment term wherever possible; otherwise, the payment comparison is misleading.
4. Co-borrower financing: best for genuinely shared ownership
A co-borrower applies with you and shares responsibility for repayment. Ask the lender whether it accepts joint applications and how both applicants' credit, income, and obligations affect the decision.
This route belongs in a shared household purchase—not a casual request for someone to help you get approved. Confirm how the lender handles the loan and vehicle title, and make sure both applicants understand the contract.
Co-borrower financing pros:
- Lets a lender evaluate a joint application where permitted.
- Fits buyers who genuinely intend to share repayment.
- Encourages a joint discussion about the household budget.
Co-borrower financing cons:
- Both borrowers face repayment obligations.
- Missed payments can affect both borrowers' credit.
- A personal disagreement does not erase the loan contract.
Best for: Partners or household members who intend to share the RV purchase and debt.
Verdict: Hold until both borrowers understand the obligation independently. Do not add another borrower just to support a payment your household cannot comfortably manage.
5. Smaller used-RV loans: best for reducing the amount borrowed
A smaller used-RV loan is a purchase strategy as much as a financing option. Choosing a less expensive RV reduces the purchase amount before interest enters the calculation; it does not automatically produce better loan terms.
For buyers who do not need a large bunkhouse or residential-style floorplan, a smaller travel trailer deserves consideration. Compare actual condition and towing requirements rather than assuming every small trailer is easy to tow or inexpensive to maintain.
Smaller used-RV loan pros:
- Reduces the amount borrowed when the purchase amount is lower.
- Lets you prioritize essential sleeping and storage needs.
- Keeps the discussion focused on budget rather than maximum approval.
Smaller used-RV loan cons:
- Repairs can offset purchase savings.
- Older vehicles can face lender eligibility restrictions.
- A smaller floorplan can limit sleeping space and storage.
Best for: First-time, seasonal, or returning campers who value manageable debt more than extra space.
Verdict: Buy only after inspection, towing checks, and an acceptable written loan offer. A lower purchase amount is not a bargain if the RV needs work you cannot fund.
How these financing options are ranked
The 2026 ranking follows the criteria above: borrowing cost, payment fit, vehicle eligibility, application clarity, contract terms, and purchase readiness. Dealership financing leads as a practical starting conversation, not as a claim that it always provides the lowest-cost loan.
Credit unions and banks provide independent comparisons. Co-borrowing serves shared purchases, while a smaller used-RV loan addresses the amount borrowed. Your written offers—not this list's order—determine the financing winner.
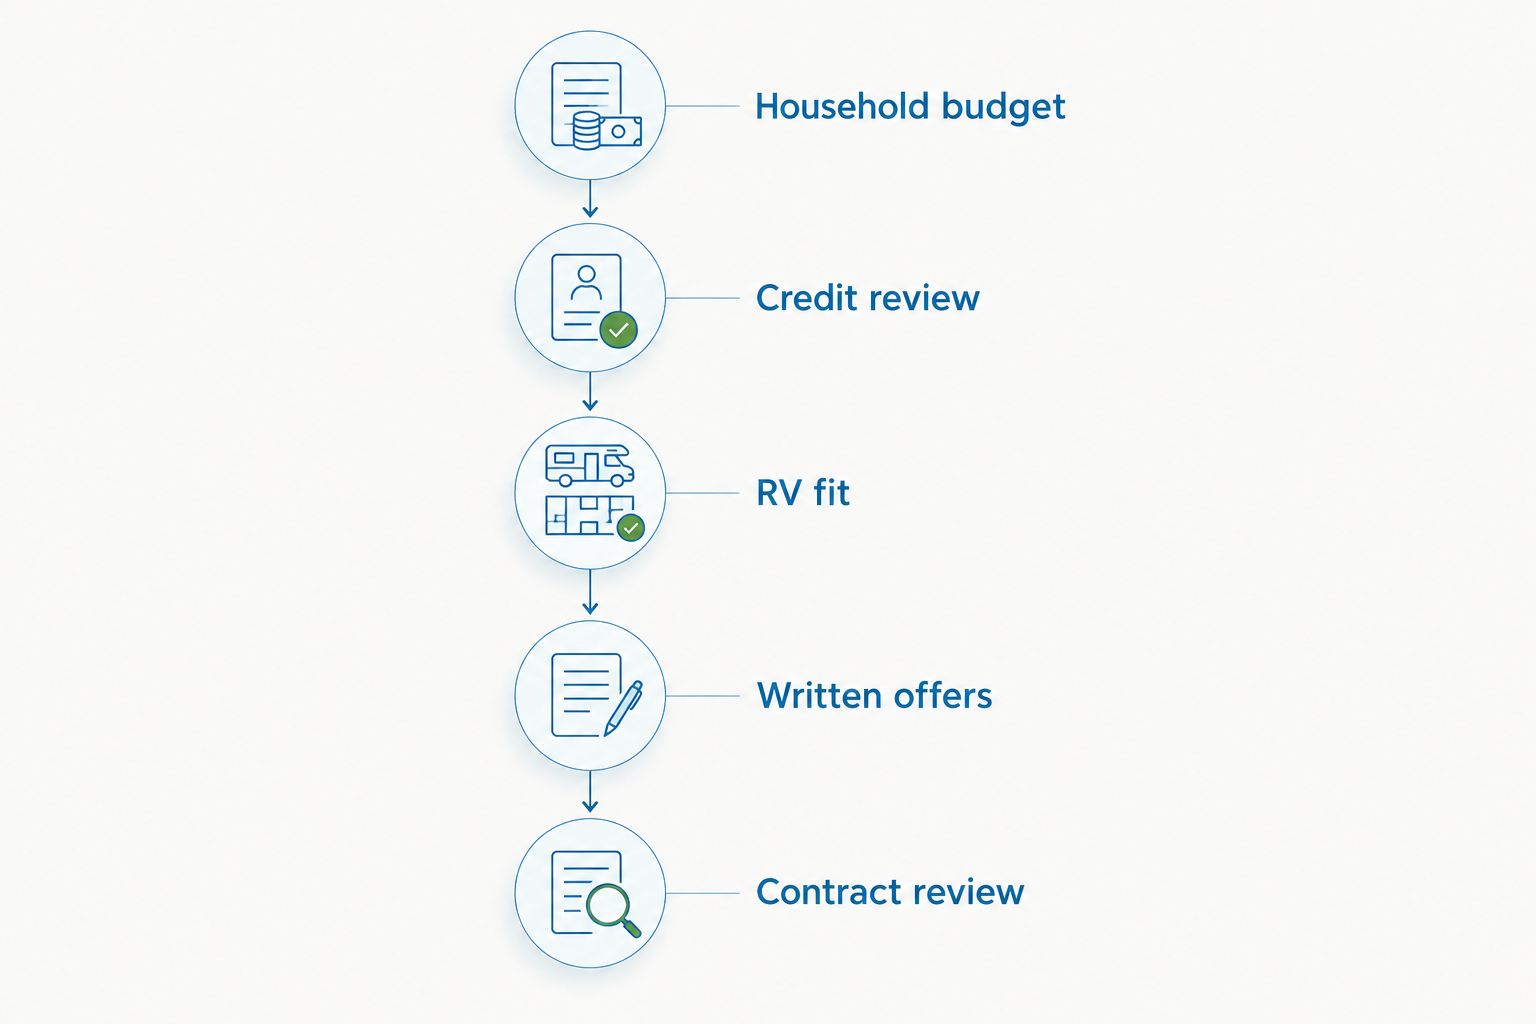
Before applying: use this purchase sequence
Follow this sequence for a 2026 purchase so the financing does not get ahead of the camping plan:
- Household budget: Build an ownership budget across 12 months, including seasonal expenses. Keep emergency savings separate from the down payment.
- Credit review: Review your credit reports and address errors through the credit reporting company's dispute process. Ask about application inquiries before authorizing them.
- RV fit: Confirm sleeping needs, storage, intended use, and towing compatibility. For a towable RV, use the vehicle and trailer documentation rather than a salesperson's shorthand.
- Written offers: Aim to compare 2 written offers if you qualify. Match the amount financed and repayment term before comparing monthly payments.
- Contract review: Check 3 documents together: the itemized purchase agreement, credit disclosures, and repayment schedule. Resolve any mismatch before signing.
For a trade-in, separate its value from its remaining loan balance. Negative equity means the payoff exceeds the trade-in value; if that difference enters the new loan, it adds debt without adding value to the replacement RV.
Full-time and seasonal buyers should also state their intended use when asking about financing and insurance. Do not assume terms written for one use automatically cover another.
Discuss your RV purchase
Talk with a family-owned Myrtle Beach-area dealership about RVs, financing, trade-ins, and service.
Which RV financing option should you choose?
Start with a dealership financing discussion, then compare a direct-lender offer if you qualify. Existing credit union members should ask their institution first or alongside that conversation. Buyers who genuinely share ownership can investigate a joint application.
If the only workable payment requires stretching the term beyond your comfort level, reduce the purchase amount or wait. Approval does not require you to buy.
Before calling the Myrtle Beach-area lots, write down your intended use, tow vehicle, trade-in payoff, and comfortable payment range. Recreation USA offers travel trailers and fifth wheels alongside other RV types; ask about a floorplan that fits your camping needs before discussing a larger purchase.
FAQ
What's the best RV financing for bad credit in 2026?
The best RV financing for bad credit in 2026 is the qualifying offer that fits your ownership budget and has acceptable total borrowing costs. Start with a dealership financing discussion and compare a credit union or bank offer if you qualify.
Can I finance an RV with bad credit?
Bad credit does not establish whether a particular lender will approve your RV loan. The lender evaluates your application, repayment capacity, and chosen vehicle; ask about its requirements before applying.
Is a credit union better than dealership RV financing?
A credit union is better only when its written offer fits your needs better than the dealership-arranged alternative. Compare the annual percentage rate, amount financed, repayment term, and total payments rather than assuming either route wins.
Does a bigger down payment guarantee RV loan approval?
A bigger down payment does not guarantee RV loan approval. It reduces the amount you need to borrow, but the lender still evaluates the application and vehicle.
Can a co-borrower help with an RV loan?
A co-borrower lets a lender consider a joint application where permitted, but does not guarantee approval. Both borrowers must understand their repayment obligations and how missed payments affect them.
Is a used travel trailer better for a tight financing budget?
A used travel trailer fits a tighter financing budget when its purchase amount, condition, and ownership expenses suit your finances. Inspect it before committing, and confirm that the lender accepts the particular vehicle.
Does Recreation USA offer RV financing near Myrtle Beach?
Recreation USA offers RV financing and sells new and used RVs at two lots in the Myrtle Beach area. Ask about the application process and written terms; financing is not guaranteed.
Should I wait if the only RV loan offer feels unaffordable?
Wait if the RV loan and ownership expenses do not fit your household budget. Reducing the purchase amount or addressing credit-report errors is a better next step than accepting a payment you cannot sustain.
One last thing
An approval is permission to borrow, not a reason to spend. Before signing a 2026 RV loan, decide what you would remove from your household budget if camping expenses or repairs increased. If the answer involves essentials, choose a smaller purchase or wait.
A suitable travel trailer or fifth wheel should fit both your camping plans and your towing setup. Financing the wrong RV does not become a good decision because the payment looks manageable.