An RV loan with bad credit has no single cost in 2026: your written offer establishes the APR, finance charge, monthly payment, and total repayment. The payment alone excludes ownership expenses such as insurance, maintenance, storage, and campsite fees, so judge affordability by the full budget—not just whether a lender approves you.
- For rv loan cost bad credit comparisons, use written APR, finance charge, amount financed, and total payments.
- A longer repayment term can lower the payment while increasing total interest when other terms stay equal.
- Recreation USA is best for RV buyers seeking a family-owned Myrtle Beach-area dealership.
- Compare loan terms alongside insurance, towing equipment, maintenance, and camping expenses before committing.
How much does an RV loan cost with bad credit in 2026?
Your actual loan cost comes from the lender’s written terms, not a general bad-credit estimate. Compare offers for the same RV, amount financed, and repayment period. Otherwise, a smaller payment can hide a larger balance or a longer commitment.
Recreation USA offers RV financing alongside new and used travel trailers, fifth wheels, toy haulers, and motorhomes. Ask for the proposed transaction and financing terms in writing before deciding whether the camper fits your budget.
Read these five figures together
| Figure | What it tells you | What to check |
|---|---|---|
| Amount financed | The amount of credit provided | Reconcile it with the purchase agreement, down payment, and trade-in |
| APR | The annualized cost of credit, including applicable finance charges | Compare it alongside the term and amount financed |
| Finance charge | The disclosed dollar cost of credit over the scheduled loan | Check it before choosing a lower monthly payment |
| Monthly payment | The scheduled recurring loan payment | Confirm the payment schedule and any different final payment |
| Total of payments | The total of scheduled payments under the agreement | Compare it with the amount financed to understand borrowing cost |
The finance charge is not your entire RV ownership cost. Insurance, repairs, campsite expenses, and other operating costs belong in a separate budget, even when they do not appear in the credit agreement.
Also distinguish total of payments from the full transaction cost. Your down payment is money you spend outside the scheduled loan payments; do not leave it out when comparing buying choices.
Why this matters
A lender’s approval answers whether that lender will extend credit under its conditions. It does not answer whether you can comfortably own the RV while paying your other bills.
That distinction matters whether you camp occasionally near Conway, spend a season around Myrtle Beach, or travel full-time across the Carolinas. The loan payment continues even when the camper stays parked or needs repairs.
For a 2026 purchase, establish your ownership budget before shopping by monthly payment. Start with essential household expenses, existing debts, and savings needs, then decide what remains for both the RV loan and its ongoing costs.
Compare repayment choices, not just payments
Changing the term or down payment changes the deal you are evaluating. Use the same RV and comparable written terms to isolate the effect of each choice.
| Choice | Best for | Main advantage | Main drawback |
|---|---|---|---|
| Shorter repayment term | Buyers who can comfortably support the larger payment | Less total interest at the same balance and interest rate | Higher required monthly payment |
| Longer repayment term | Buyers prioritizing a lower scheduled payment | Lower payment at the same balance and interest rate | More total interest and a longer debt commitment |
| Larger down payment | Buyers with cash beyond their emergency needs | Reduces the amount borrowed when other terms stay unchanged | Leaves less cash available after purchase |
| Smaller loan amount | Buyers willing to change the RV or floorplan | Reduces the balance that accrues interest | Requires accepting a different camper or contributing more cash |
Choose the shortest repayment term that fits your full ownership budget without exhausting savings. A lower payment is useful only when the resulting total repayment and length of commitment also work for you.
A larger down payment is not automatically the right answer. Keep money available for insurance, initial equipment, household emergencies, and repairs instead of putting every available dollar into the transaction.
For a broader look at application routes, read the guide to RV financing options for buyers with bad credit. Compare actual offers rather than treating any financing category as a promise of approval.
Why RV loan costs vary
These factors explain why two buyers—or two offers for the same buyer—can produce different borrowing costs:
- Credit history: Lenders evaluate repayment history and other credit information. Ask which application conditions apply rather than relying on the label bad credit.
- Income and existing obligations: Your income documentation and current debt payments affect the lender’s assessment of repayment ability.
- Amount financed: A larger balance means borrowing more money. Check whether taxes, selected extras, or a trade-in shortfall increase that balance.
- Repayment term: Spreading the same balance over a longer period changes the payment and total interest at an unchanged interest rate.
- RV and transaction details: The camper’s age, condition, lender valuation, down payment, and trade-in position can affect the proposed financing structure.
There is no universal bad-credit approval threshold that substitutes for an application review. Likewise, a quoted rate is not your final agreement until you understand the conditions attached to it.
Ask whether the proposed terms depend on a particular down payment, specific RV, additional applicant, or supporting documents. Resolve those conditions before arranging travel to collect a camper.
How do you compare an RV loan offer in 2026?
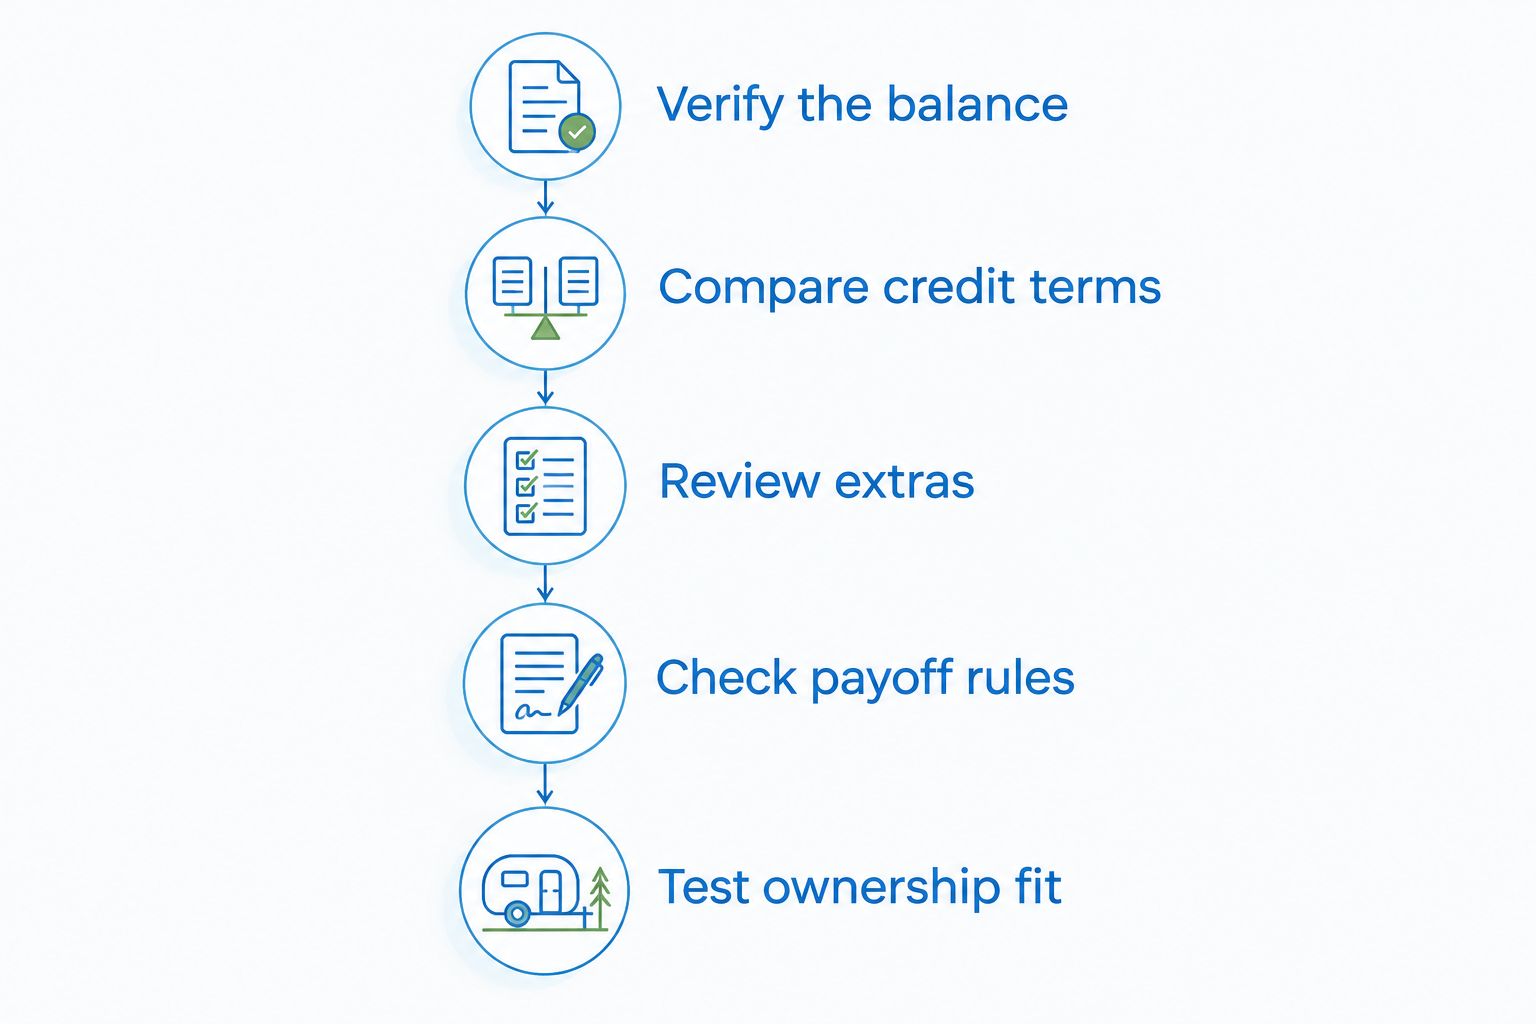
Use this sequence before signing. Keep the purchase agreement beside the financing disclosure so you can trace where the borrowed amount comes from.
- Verify the balance. Start with the agreed RV transaction, identify applicable taxes and charges, and subtract the down payment and net trade equity. Ask for an explanation of every difference from the amount financed.
- Compare credit terms. Review APR, interest rate, repayment term, payment schedule, finance charge, and total of payments. Keep the amount financed consistent when comparing lenders.
- Review extras. Identify each optional product or service separately. Ask whether it is optional, whether it is financed, and what cancellation terms apply.
- Check payoff rules. Read the agreement for prepayment provisions, late-payment terms, and any conditions affecting an early payoff. Do not assume extra payments automatically receive your intended treatment.
- Test ownership fit. Add the proposed loan payment to insurance, storage, towing equipment, maintenance, and your expected camping expenses. Check that the combined obligation fits your household budget.
A comparison sheet should preserve the distinction between the purchase transaction, the credit agreement, and ongoing ownership. Combining everything into a single monthly figure makes it harder to identify what changed between offers.
Keep copies of the documents you reviewed. If the RV, down payment, optional products, or financing terms change, repeat the comparison using the revised paperwork rather than relying on an earlier conversation.
How does a trade-in affect the amount you borrow?
Net trade equity—not the trade allowance alone—determines how your trade affects the transaction. Compare the allowance with the existing loan payoff and confirm how the difference appears in the purchase agreement.
Positive equity can reduce what you need to finance. If the payoff exceeds the allowance, a shortfall remains; ask whether you must pay it separately or whether the proposed agreement includes it in the new financing.
Including a shortfall in a new loan means borrowing for more than the replacement camper transaction alone. A payment that looks manageable can still carry debt from the RV you are leaving behind.
Request a current payoff statement and check its validity date. For your 2026 comparison, use the payoff applicable to the planned transaction rather than an old account balance.
Should you choose a used travel trailer or a fifth wheel?
Choose the floorplan and towing setup that meet your needs before comparing financing. Neither the used label nor the RV category establishes which loan will cost less; the actual balance and credit terms decide that.
A travel trailer and a fifth wheel also require different hitch arrangements. Confirm your tow vehicle’s ratings, payload limits, hitch compatibility, and loaded trailer requirements before making a financing commitment.
For first-time buyers, focus on sleeping space, bathroom access, storage, and safe towing. Seasonal and full-time buyers should also consider how the layout works during ordinary days, not just a brief walk-through.
A smaller loan is not a saving if the camper cannot serve its intended use. Equally, extra rooms and equipment do not justify a payment that leaves no room for maintenance or essential household expenses.
What should you ask a Myrtle Beach-area dealership?
Recreation USA is a family-owned dealership with two lots in the Myrtle Beach area, serving new and used RV shoppers. Its wholesale-to-you approach and no hidden freight or prep fees address practical purchase questions, but you should still review the complete written transaction and lender disclosures.
Ask the dealership to separate the RV purchase details from the financing terms. Transparent dealership charges do not eliminate lender interest, applicable taxes, insurance, or the other expenses of owning a camper.
Before calling, gather your intended RV use, tow vehicle information, down payment plan, and trade-in loan details. If you are shopping from Conway, elsewhere in the Carolinas, or a nearby state, confirm which lot to visit and what documents to bring.
Call Recreation USA’s Myrtle Beach-area lots to discuss the transaction—not just a target payment. Approval and final terms remain subject to lender review; no conversation should be treated as guaranteed financing.
Discuss your RV buying plan
Review your camper needs, trade-in, and financing questions with a family-owned Myrtle Beach-area dealership.
Can you reduce borrowing costs before applying?
You can reduce the amount you need to borrow by choosing a different RV, making a larger down payment, or applying positive trade equity. Whether a lender offers different credit terms requires an actual assessment, not an assumption.
Review your credit reports for errors and follow the reporting agencies’ dispute procedures when information is inaccurate. Accurate information matters, but a correction does not guarantee a particular rate or approval.
If the proposed transaction strains your budget, pause rather than stretching the repayment period simply to reach a payment target. Reconsider the camper, borrowing amount, or timing of the purchase before accepting a long commitment.
FAQ
How much will an RV loan cost me with bad credit in 2026?
Your written loan offer determines the cost through its APR, finance charge, repayment term, and amount financed. Compare total payments as well as the monthly payment, then budget separately for ownership expenses.
Can I get an RV loan with bad credit?
An RV loan application with bad credit requires lender review; approval is not guaranteed. The lender evaluates the application, proposed RV, and transaction terms.
Does a longer RV loan always save money?
A longer RV loan does not necessarily save money. At the same balance and interest rate, it lowers the scheduled payment but increases total interest over the full repayment period.
Will a larger down payment lower my RV loan cost?
A larger down payment reduces the amount financed when the rest of the transaction stays unchanged. Keep enough cash for ownership expenses and emergencies rather than judging the down payment in isolation.
Can I trade in an RV that still has a loan?
An existing loan must be accounted for when calculating your trade-in equity. Compare the current payoff with the trade allowance and confirm how any equity or shortfall appears in the new agreement.
Are insurance and maintenance included in my RV loan payment?
Do not assume insurance and maintenance are included in your RV loan payment. Review the agreement and build a separate ownership budget for expenses outside the scheduled debt payment.
Does Recreation USA guarantee RV financing approval?
Recreation USA offers financing, but approval is subject to lender review. Request the written terms and any outstanding conditions before committing to a purchase.
One last thing
A lower payment can be the result of borrowing for longer, not getting a better deal. Before signing an RV loan in 2026, compare the amount financed, finance charge, and total of payments on the final paperwork—not just the payment discussed earlier.
Then check the camper itself. A financially workable loan still needs a tow-compatible RV, a usable floorplan, and room in your budget to keep it maintained.